A VAT refund in Vietnam can release cash tied up in export purchases or an investment project. A credit balance alone is not enough: the business must qualify under a refund category, calculate the eligible amount and submit the correct dossier.
For foreign-owned companies, the main questions are practical. Which purchases qualify? What forms are required? What happens if the tax authority checks the claim before paying? This guide covers those points under the current VAT and tax-administration framework.
Which Businesses Can Claim a VAT Refund?
For the main business categories, the claimant must use the VAT credit method, maintain compliant accounting records and hold a bank account under its tax identification details. Decree 181/2025/ND-CP sets out these conditions and the refund categories.
| Category | Main eligibility rule | Practical implication |
| Exported goods and services | Eligible uncredited input VAT of at least VND 300 million, after relevant offsets | Separate export input VAT from domestic activity and support the export treatment |
| Qualifying investment project | Eligible investment-stage input VAT remaining after offset of at least VND 300 million | Review project status, capital contributions and licences before filing |
| Production of goods or provision of services subject to the reduced statutory rate | Relevant uncredited input VAT of at least VND 300 million after 12 consecutive months or four consecutive quarters for the 5% category | Mixed-rate businesses must calculate and allocate the eligible input VAT; trading activity should not be treated as qualifying production |
| Dissolution or bankruptcy | An eligible excess payment or uncredited input VAT balance under the applicable closure rules | Complete the tax and business-closure procedures; an investment project stopped before operating has separate restrictions |
A domestic trading company should therefore not assume it can obtain a cash refund simply because purchases exceed sales. Identify the legal category before building the application.
Export Claims: Allocation and the Revenue Cap
Keep export input VAT separately identifiable. Where purchases support both exports and domestic sales and cannot be directly separated, the rules use the relevant revenue allocation. Offset domestic VAT payable as required before determining the refundable export balance.
The export refund cap is 10% of export revenue. Eligible VAT above the cap carries forward for the next period’s calculation. Goods imported and then re-exported to another country are excluded from this export-refund category; imported materials used to manufacture or process exports are treated differently.
Illustrative calculation: assume eligible export revenue of VND 8 billion and qualifying input VAT of VND 900 million after the required offsets. Applying the linked statutory cap gives a maximum refund of VND 800 million. The remaining VND 100 million carries forward.
Investment Claims: Capital and Completion Matter
The category covers qualifying new and expansion projects during the investment stage. A project that does not create fixed assets is excluded. A company that has not contributed its registered charter capital in full at filing falls within the non-refund cases, as do specified projects that fail conditional business requirements and certain resource or mineral projects.
For eligible investment-stage VAT not yet refunded when the project or relevant phase is completed, the filing window is one year from completion. The decree ties completion to the relevant first revenue, excluding specified trial-run and other incidental revenue. Finance teams should record that trigger rather than waiting until the whole factory expansion is administratively closed.
What Changed in the Current Rules?
The tax-administration framework effective 1 July 2026 introduced the current declaration-linked refund forms and processing rules. Businesses should not automatically reuse an old standalone refund-request template for every claim.
For deferred-payment purchases within the non-cash-payment requirement, Decree 144/2026/ND-CP addresses purchases valued at VND 5 million or more, including VAT. Input VAT can be deducted before payment falls due where the conditions are met. If qualifying payment evidence is missing at the contractual due date, the deduction must be adjusted down; a later qualifying payment supports deduction in the payment period.
This makes payment schedules part of the refund review. Match each invoice to its due date, amendments and settlement evidence before including its VAT in the claim.
Required Forms and Documents
Forms for the Main Business Refund Categories
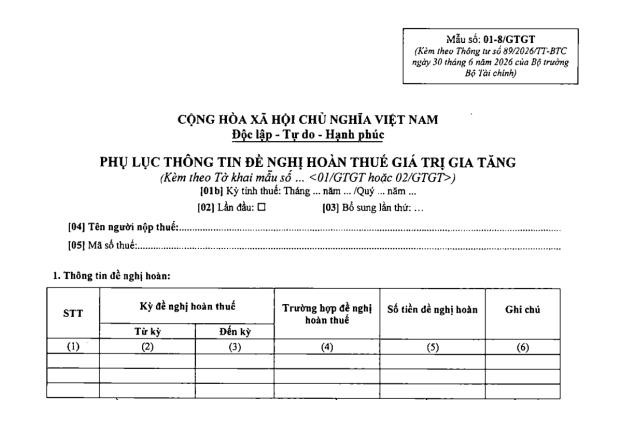
Article 46 of Circular 89/2026/TT-BTC specifies the following forms:
| Claim | Return | Refund appendix |
| Exports | 01/GTGT, with the refund field completed | 01-8/GTGT |
| Investment project | 02/GTGT, with the refund field completed | 01-8/GTGT |
| Qualifying production or services in the reduced-rate category | 01/GTGT, with the refund field completed | 01-8/GTGT |
Additional Documents for an Investment Project
Prepare the following project documents required by Article 46:
- The investment registration certificate, investment certificate or licence where required; investment-policy approval where applicable; or the owner’s project-establishment decision where neither approval route applies.
- For construction projects, the land-use certificate, land-allocation or lease decision, or land-lease contract, plus the building permit where required.
- Evidence of charter-capital contributions.
- The conditional-business licence, certificate or approval where already required and issued during the investment stage.
- Where a project management board, branch or newly established entity files, the applicable establishment, operating and project-assignment documents specified for that structure.
These supporting project documents are submitted with the first claim or when changed or supplemented. Keep the full current set in the company’s records even when a later application does not need every item resubmitted.
Records to Prepare for Verification
The prescribed application forms and the evidence supporting the VAT calculation serve different purposes. Keep an indexed working file containing:
| Record | What the finance team should reconcile |
| Purchase invoices and import tax records | Supplier identity, purchaser details, VAT amount, business use and ledger entry |
| Payment evidence | Bank settlement, payment due dates, permitted offsets and any third-party payment agreement |
| Export file | Customer contract, invoice, customs declaration for goods where required, delivery evidence and export receipt |
| VAT calculation | Opening credit, current input VAT, domestic offsets, allocation, prior refunds and the requested balance |
| Project file | Project scope, capital payments, approvals, construction records and the investment-stage cut-off |
For exported services, keep evidence showing that the service meets the legal export conditions; a foreign customer or foreign-currency invoice alone does not establish where the service is consumed.
How to Apply for a VAT Refund in Vietnam
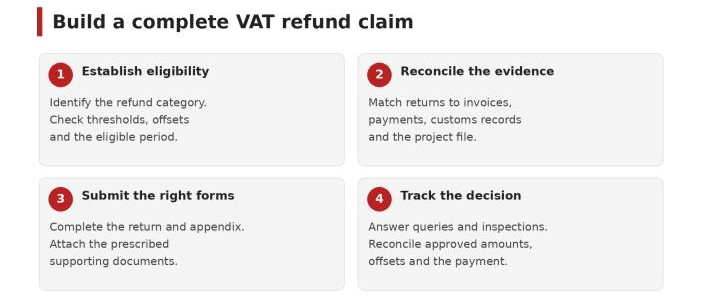
Step One: Confirm the Category and Claim Period
Identify the claimant, category and period. Check that the amount has not already been refunded or carried into another inconsistent claim. For a completed investment phase, record the filing deadline at this stage.
Step Two: Reconcile the Claim
Tie the proposed refund to the VAT returns, general ledger, invoices, customs documents and payment records. Explain differences such as bank charges, credit notes and partial settlements with the relevant contract or reconciliation evidence.
Step Three: Complete and Submit the Dossier
Submit the applicable return, refund appendix and supporting documents through the tax authority’s electronic filing system using the business’s registered credentials and digital signature. The directly managing tax authority generally handles the claim; investment claims go to the authority receiving the project’s VAT returns.
Save the submission acknowledgement and application reference. Where the refund dossier also serves as the tax return, the return-acceptance notice also serves as the refund-dossier acceptance notice under the current rules.
Step Four: Answer Queries or Support an Inspection
Assign a person responsible for notices, reconciliations and document delivery. Respond to each issue with the relevant invoice, payment, contract or ledger reference. Keep a log of the request, response and supporting attachment so later questions can be traced.
Step Five: Reconcile the Decision and Payment
Check the approved amount, any tax-debt offset and the payment received. Record any amount disallowed, carried forward or still under examination separately, and update the VAT ledger to prevent duplicate claims.
VAT Refund Processing Times
Article 31 of Decree 252/2026/ND-CP uses different starting points for each stage:
| Stage | Statutory timing | What it means for cash-flow planning |
| Dossier acceptance or refusal | Three working days from receipt | The authority assesses whether to accept the dossie |
| Refund-first case | Six working days from the acceptance notice | The authority can refund, refuse, identify an ineligible amount or move the case to inspection |
| Inspection-before-refund case | Ten working days after the inspection conclusion or violation-handling decision | This is the post-inspection decision period, not the total time from filing |
Time spent by the taxpayer explaining or supplying additional information is excluded where the rules specify. Keep a cash buffer while the claim is reviewed.
First claims by project or refund category, high-risk claims or amounts, and dissolution or bankruptcy claims fall within inspection-before-refund rules. Recent tax-evasion cases are also addressed, with specific exceptions after a clean review. Do not assume an earlier refund for a different project puts a new project on the refund-first route.
Common Reasons a Claim Is Delayed
- The refund appendix does not reconcile to the filed return or ledger.
- Export revenue, customs records and receipts use inconsistent customer or contract references.
- A deferred-payment invoice has passed its due date without qualifying settlement evidence.
- The project dossier lacks capital-contribution evidence or the relevant approval.
- Shared purchases have been allocated without a clear calculation.
- The submission uses forms for the wrong tax period or transition route.
For historical periods, Article 100’s transition rules matter. Returns for periods before the current framework and previously accepted applications can remain under earlier forms or procedures. A pre-transition return with a refund field already completed but no refund dossier submitted has a specific transition tied to the tax system’s implementation timetable. Identify the original period and submission status before selecting forms.
Conclusion
A well-prepared VAT refund claim connects the legal category to a clear calculation and a complete evidence file. Resolve invoice, payment and project-document issues before filing, and plan cash flow around the correct review route. InCorp Vietnam’s VAT refund services can help assess eligibility, prepare the dossier and manage queries. For the wider accounting records behind a claim, explore our bookkeeping services.
Learn the Right Setup for Business
Expansion in the Vietnam
Frequently Asked Questions
Can a foreign-owned company claim a VAT refund in Vietnam?
- Yes, if it meets an eligible refund category and the accounting, invoice, payment and other requirements. Foreign ownership alone neither creates nor removes entitlement.
Is the entire input VAT balance refundable?
- No. The eligible category, allocation, domestic offsets and any refund cap determine the amount. Amounts outside the current claim may carry forward where the rules allow.
Which form should an exporter use?
- Under the current procedure, the exporter completes the VAT return's refund field and submits the refund appendix identified in the forms table above. Historical periods must be checked against the transition rules.
How long does an inspected refund take?
- The inspection must be completed before the post-inspection decision period starts. The timing table explains that starting point; it should not be read as a promise of payment shortly after the original filing.
Is a business VAT refund the same as an airport shopping refund?
- No. This guide covers company input VAT. Refunds for qualifying goods carried out of Vietnam by eligible foreign travellers follow the separate departure-shopping procedure.